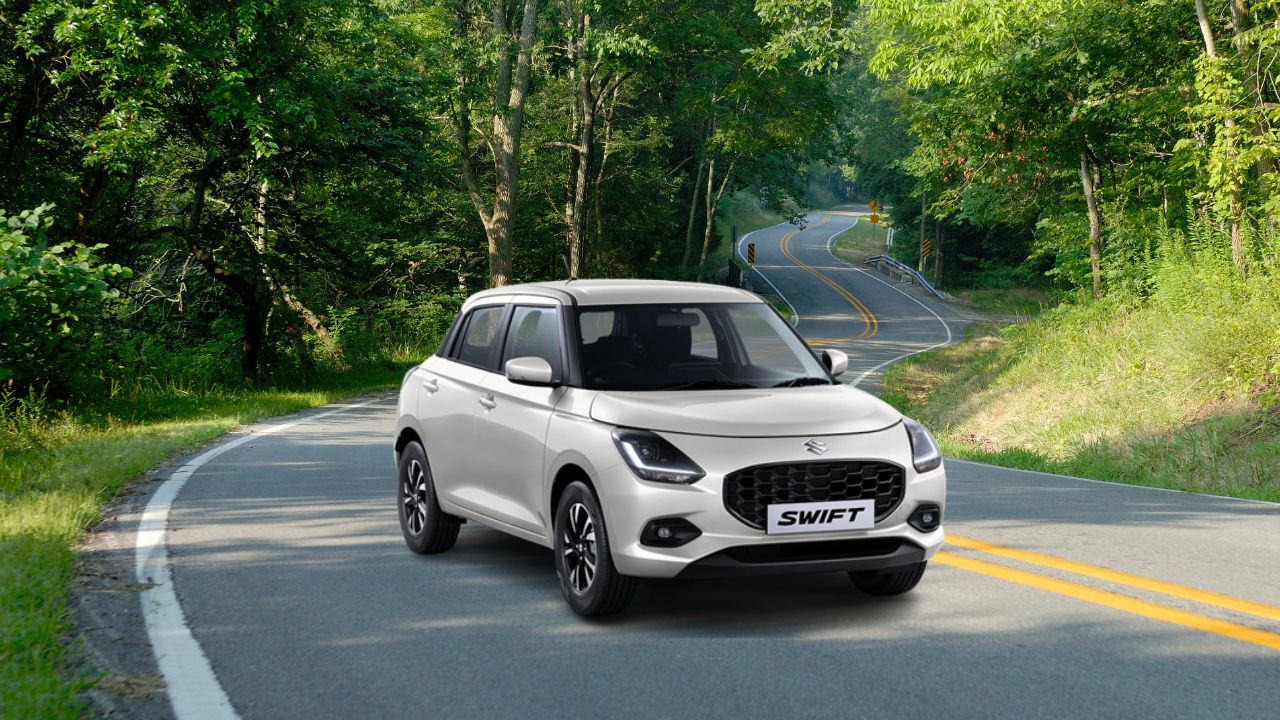
Employees often get confused about what salary they need to buy a Maruti Suzuki Swift. Its on-road price provided by the dealer will be more than a sticker price, depending on the city charges and insurance. To buy it, take-home is ₹50,000 when an EMI of ₹11,200 is set to your account. That EMI already eats about 22% of your salary before fuel, insurance renewals or a single service bill.
So plan your swift according to your salary, understand how you can take up a loan that won’t squeeze your account.
What Salary Do You Need to Buy a Maruti Suzuki Swift
If your salary is around ₹50,000 to ₹60,000 a month excluding EPF and you make a reasonable down payment then you can easily purchase a Swift. If you have any major EMI to pay along with your car EMI, it could go rough on your daily expenses. If your salary is roughly ₹40,000 a month then it’s possible to buy a Maruti Suzuki Swift but you’ll need a bigger down payment and tight budget for the first couple of years.
Lenders are more generous than that. Many will approve a car loan of roughly three to four times your annual income, which means someone earning about ₹2.89 lakh a year could theoretically qualify for a Swift loan. Approval tells you what the bank will risk. It says nothing about what your month looks like after the EMI leaves your account.
Maruti Suzuki Swift On-Road Price
The ex-showroom price range of Swift is ₹5.79 lakh to ₹8.69 lakh for the top variant. There are a total 12 variants which also come in this price range. A 1.2 Petrol LXI is the base variant which can be easily bought. Check the price because it updates with time and ask your dealer the cost of a car because each city applies different charges.
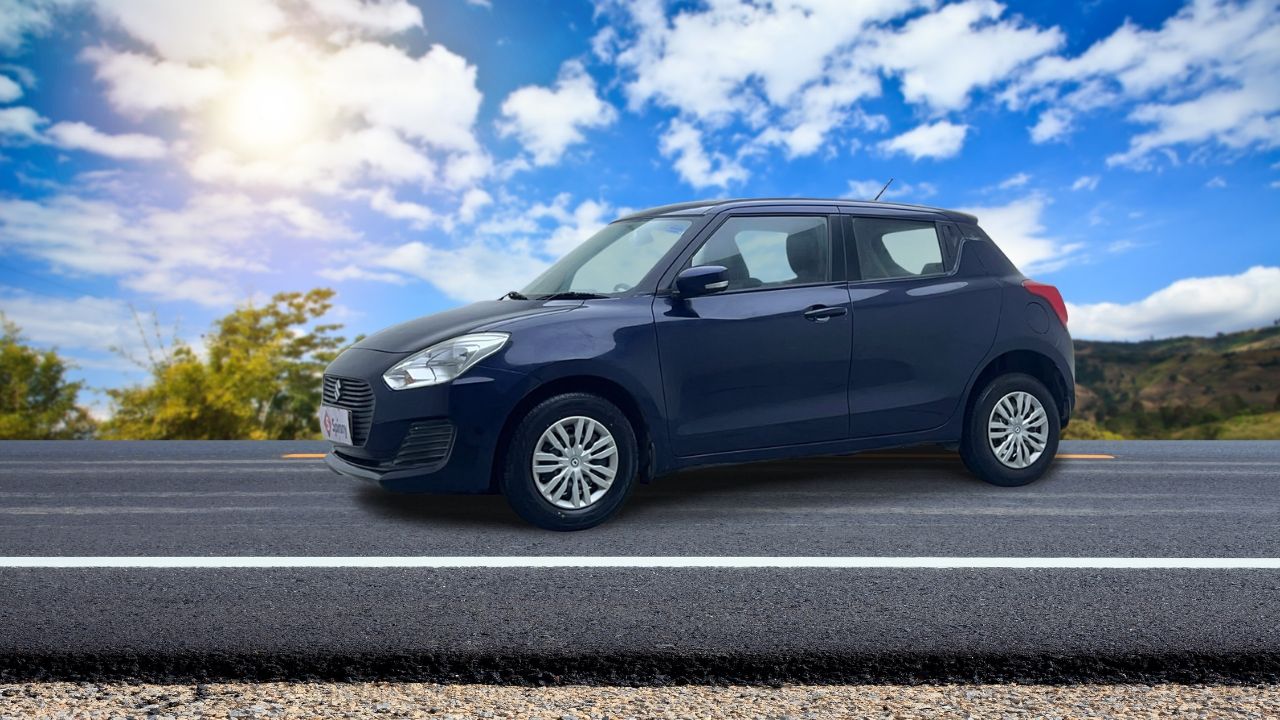
The base LXI is nearly cost around ₹6.69 to ₹10.04 lakh in Mumbai and ₹6.44 lakh in Delhi. For the math below I’ve used ₹6.7 lakh, the figure for an entry-level Swift in a metro. The CNG version price starts at ₹7.45 lakh ex-showroom in Delhi and the automatic variant costs around ₹7.04 lakh.
What EMI Is Comfortably Fit With Your Salary
Assuming a five-year loan with a 9.5% interest which works out to roughly ₹2,100 of EMI for every ₹1 lakh borrowed. The loan interest and tenure depends on your credit score and lender.
| Monthly take-home | Down payment | Loan amount | EMI | EMI as share of salary | Verdict |
| ₹40,000 | ₹2.0–2.5 lakh | ₹4.2–4.7 lakh | ₹8,800–9,800 | 22–24% | Possible, but tight |
| ₹50,000 | ₹1.35 lakh | ₹5.35 lakh | ₹11,200 | 22% | Manageable with few other expenses |
| ₹60,000 | ₹1.5–2.0 lakh | ₹4.7–5.2 lakh | ₹9,800–10,900 | 16–18% | Comfortable |
| ₹70,000+ | ₹1.5–2.0 lakh | ₹4.7–5.2 lakh | ₹9,800–10,900 | 14–16% | Comfortable, with room for running costs |
The usual rule is to keep a car EMI within 15 to 20% of take-home pay, and closer to ₹8,000–₹10,000 if you pay rent or carry other loans. By that rule, the ₹50,000 row only works if you change the down payment. To bring the EMI under ₹10,000 on a ₹6.7 lakh on-road price, you’d borrow about ₹4.75 lakh, which means putting down nearly ₹1.95 lakh instead of ₹1.35 lakh. A larger down payment is the cheapest way to make the Swift fit a smaller salary.
The on-road price should sit within one year’s take-home income. At ₹6.7 lakh, that points to ₹56,000 a month, which agrees with the ₹50,000–₹60,000 range above.
The Running Cost of Swift That Skips From EMI Calculator
Say you drive about 1,000 km a month. At roughly 18 to 20 km per litre in real city conditions and petrol near ₹100 a litre, that’s around ₹5,000 for fuel. These are my estimates, not tested figures, and both the mileage and the petrol price vary by city and driving style. Add a monthly reserve for servicing and insurance renewal, perhaps ₹1,500–₹2,000, and you’re near ₹7,000 a month on top of the EMI.
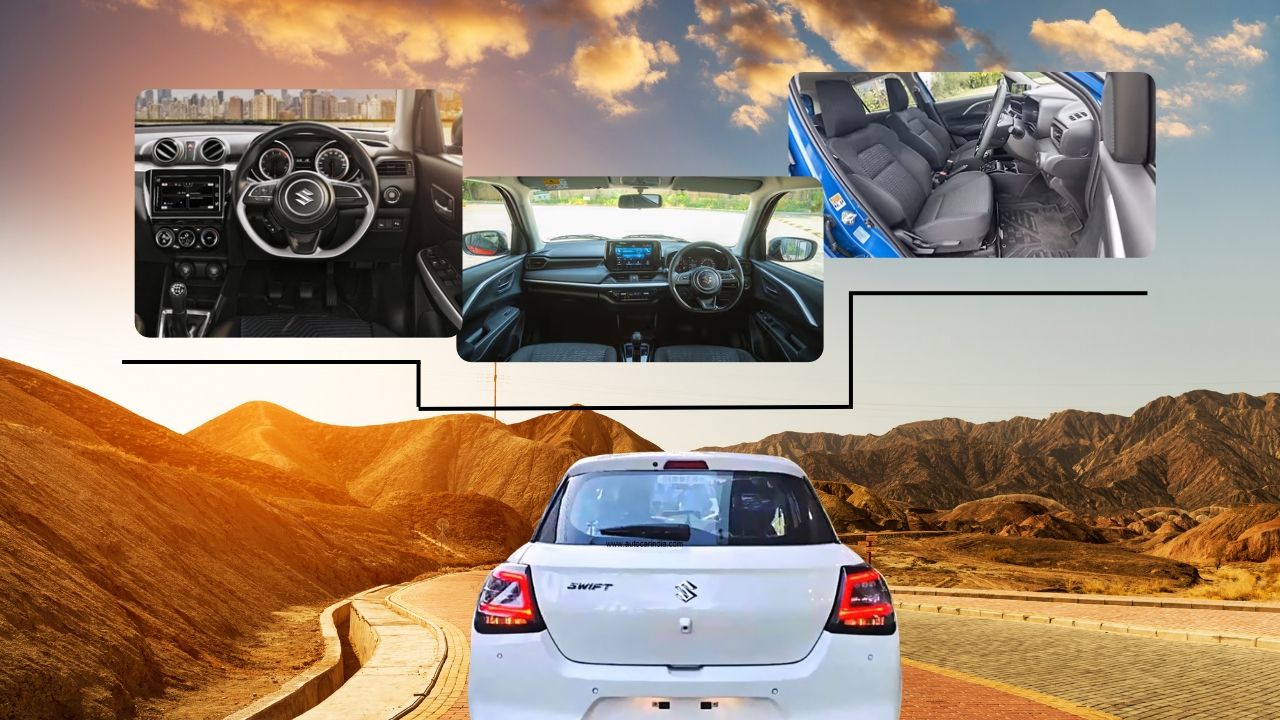
If your salary is ₹50,000 a month and total car cost (running plus EMI) near ₹18,000 that leaves 36% of take-home. If you earn ₹60,000 and EMI is ₹10,000 then the total is about ₹17,000 that leaves 28% of take home. That gap is why the salary needed to buy a Swift comfortably sits closer to ₹60,000 than ₹50,000. Parking, tolls and tyre replacement are extra, and they matter a lot in India.
Maruti Swift Specs at a Glance
| Spec | Details |
| Engine (petrol) | 1.2-litre Z-series, 3-cylinder, 82 hp, 112 Nm |
| Engine (CNG) | Same 1.2-litre, 70 hp, 102 Nm |
| Gearbox | Manual or AMT (CNG is manual only, going by the listed trims) |
| Claimed mileage | 24.8 kmpl (manual) to 25.75 kmpl (AMT); CNG 32.85 km/kg |
| Safety | Six airbags, ESC, ABS with EBD (confirm variant-wise with the dealer) |
| Ex-showroom price | ₹5.79–₹8.69 lakh |
You have to pay ₹1.5 lakh extra to purchase a CNG but you can save on fuel if you drive more. So it will recover your purchase cost in a few years. If the CNG station is fewer in your region then you can face a difficulty. Its always depends on your driving pattern and area.
Swift vs Tata Tiago vs Hyundai Grand i10 Nios
The Swift’s two nearest rivals are the Hyundai Grand i10 Nios and the Tata Tiago. Both start cheaper, though listings disagree on by how much. Tiago ranges between ₹4.70 and ₹5.60 lakh ex-showroom and the Nios between ₹5.47 and ₹5.98 lakh, so check current dealer prices.
The Nios uses a 1.2-litre Kappa petrol with around 82–83 hp, almost identical to the Swift’s output. Hyundai’s cabin is a little more polished, but the Nios has only a 2-star Global NCAP rating under the older protocol. The Tiago’s 1.2-litre Revotron is the least efficient at about 19 kmpl, and its pitch is safety and value rather than fuel economy. The Swift’s claimed 24.8 kmpl beats both comfortably.
For a stretched budget, the arithmetic helps. Choosing a Tiago over a Swift cuts the loan by about ₹1 lakh or more, which saves roughly ₹2,100 a month in EMI. Over five years that is about ₹1.26 lakh. If your take-home sits near ₹45,000, that difference matters more than the Swift’s better mileage. If you’re at ₹60,000 and want the stronger resale value and mileage, the Swift is the easier choice.
What Are The Monthly Running And Fuel Costs
The fuel is about ₹4,000–₹7,000 in India and other charges like insurance, servicing, repair needed then the total amount to run for new petrol Maruti Suzuki Swift would be around ₹6,500–₹11,000. EMI is not included in this amount.
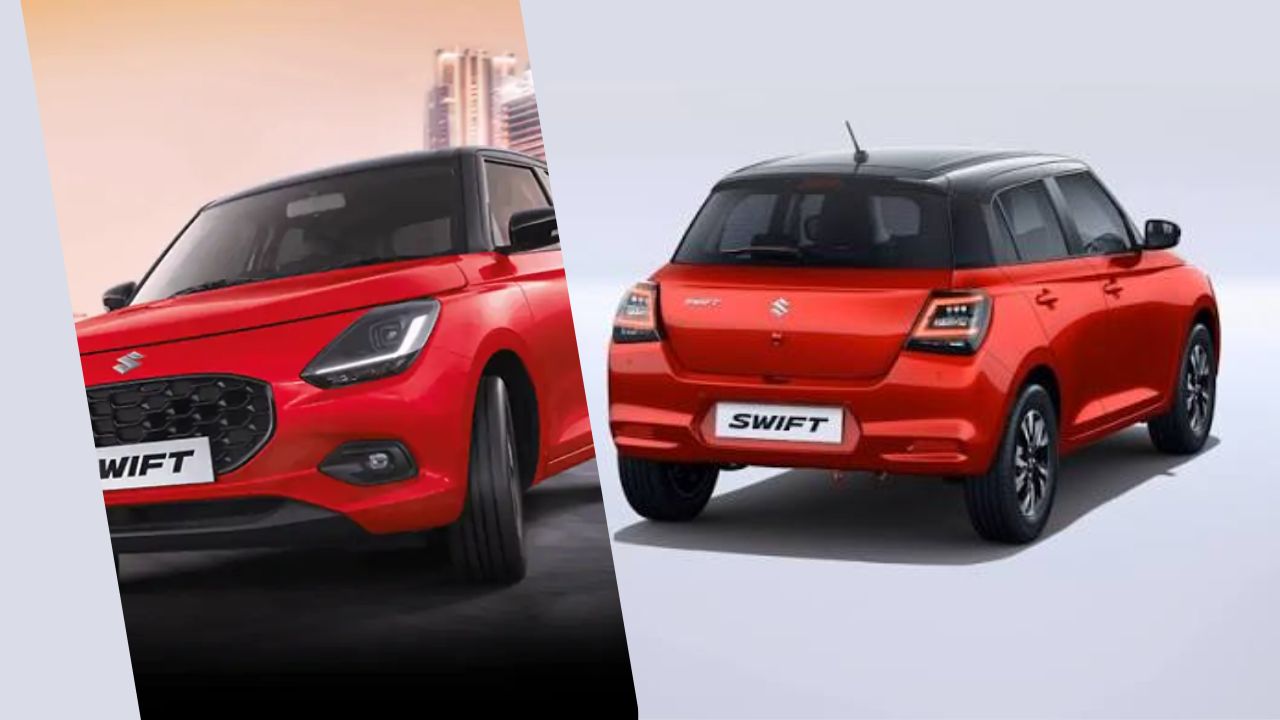
The current Swift petrol returns an ARAI mileage of about 25.35 kmpl (manual) to 26.25 kmpl (AMT). This is the claimed mileage of a car and the real-world city mileage is usually lower.
Conclusion
If you don’t have any other major EMI to pay on a ₹60,000 salary then purchasing a Swift is a great option. If you are below that salary then you have to be careful about your expenses and running cost of a Swift to make a purchase.
Before you sign, run one test. Multiply your take-home by 12 and compare it with the on-road price from your dealer. If the price is higher, raise the down payment until the EMI drops below 20% of your monthly salary. If you can’t get there without draining your savings, you’ve found your answer.
