Most of the corporate employees posted a photo with a new BMW, and everyone wondered how someone at this age pulled it off. The simple way is usually a loan. A BMW in India costs about ₹55 lakh on the road, and to pay that kind of money from your salary is possible when you are sitting in a good position at the company.
Your six figures salary can make you eligible to afford a BMW without squeezing your savings, your home-loan eligibility, and your sleep.
Check the real cost of your chosen vehicle and city registration cost then calculate along with the way I did below here. The figures mentioned in the article are estimated on the current listing so the real cost of the car might be updated.
How Much BMW in India Costs
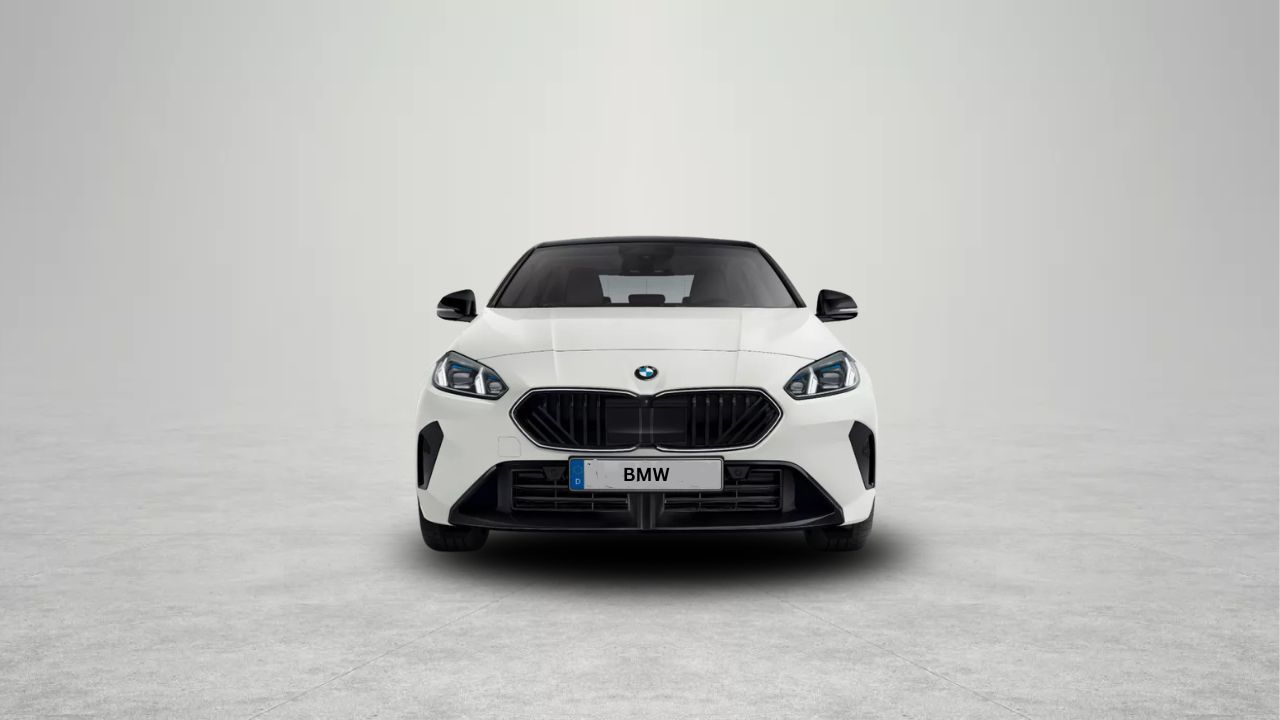
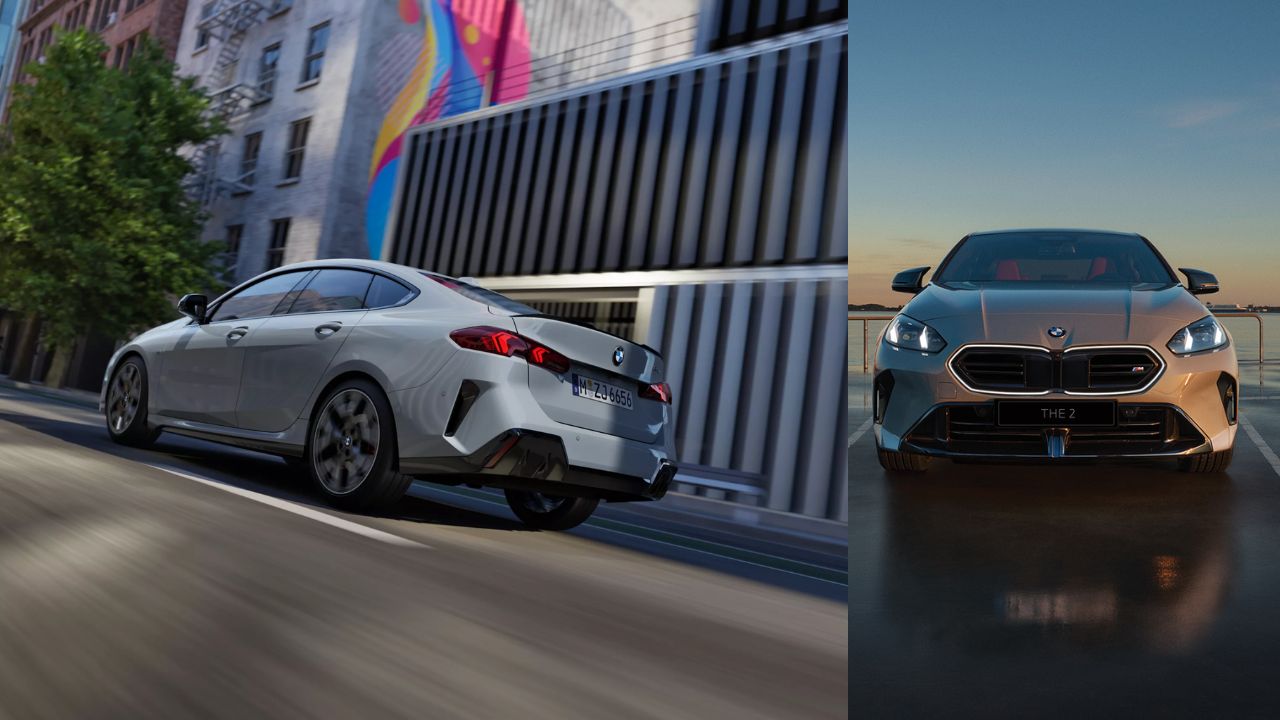
BMW 2 Series Gran Coupe comes at a lower price than other luxury cars. It launched last year in India at ₹45.80 lakh (ex-showroom) and the second variant (M Sport Pro) with more cabin specs priced at ₹48.20 lakh.
Ex-showroom is not what you pay. Registration and insurance add a lot, and both vary by state. The estimates put the on-road price around ₹53–55.8 lakh in Delhi, and up to ₹57.6 lakh in Pune.
The BMW cost you around ₹54.7 lakh on the road if you are buying from Indore. It shows how a ₹45.8 lakh car is becoming around Rs 55 lakh by adding ₹6.66 lakh registration charge, ₹1.8 lakh for insurance and additional charges around ₹46,000.
For planning, ₹55 lakh is a fair middle figure, and every number below uses it. Check your own city’s on-road quote before you commit, because a ₹5 lakh swing between states is normal.
The Loan Math Behind the ₹91,000 EMI
If you are buying a BMW with your salary then cash isn’t your way. The 20% down payment and a five-year loan agreement can be a standard and better plan.
On a ₹55 lakh car, 20% down means ₹11 lakh upfront. The rest of the ₹44 lakh loan you have to repay every month. If the interest applied on loan is 9% then the EMI will be around ₹91,000 a month in a 60 months tenure. So the total repayment amount is nearly ₹54.8 lakh including ₹10.8 lakh interest.
Interest rates can be lower but most of the car loans have 9% to 10% of interest, depending on your credit score and the lender. The difference of one percent is gonna push the EMI to about ₹93,500. The tenure period also matters, EMI cost will increase in a shorter tenure but it cuts total interest amount.
If you buy a BMW on a car loan with a down payment of ₹13.5 lakh and a 4-year tenure at 10% interest rate, it will cost you around ₹87,580 every month. The point is that the EMI is a function of how much cash you bring on day one. Every extra ₹1 lakh in down payment cuts roughly ₹2,000 from your monthly instalment on these terms.
The Costs That Arrive After the EMI
New buyers often budget for the loan and forget the car. A BMW needs fuel, insurance, tyres and servicing, and none of them are cheap.
Fuel is the smallest piece. At about 1,500 km a month, a real-world 12 kmpl and ₹100 a litre, you spend around ₹12,500 a month. Insurance is lumpier. The first year costs about ₹1.78 lakh in the Indore breakdown, and a comprehensive policy generally falls in the ₹1.5–2.5 lakh range depending on the car’s declared value and your no-claim bonus.
Spread over twelve months, that’s ₹12,000–20,000. Then comes servicing, tyres, wiper and brake replacements, and the occasional repair, which add up to a few thousand rupees a month on average.
Together, plan on ₹20,000–30,000 a month beyond the EMI. Add that to ₹91,000 and your total monthly car cost is about ₹1.15–1.20 lakh.
How Much Salary Do You Need for a BMW in India?
Personal-finance planners commonly say all car costs, meaning EMI, fuel and insurance, should stay within 15–20% of your monthly take-home pay. That’s a rule of thumb, not a law, but it exists for a reason. Anything above it starts eating into the money meant for your home loan, investments and emergency fund.
Calculate your monthly expenses including your car expenses, if you pay ₹1.2 lakh a month in car costs so it will eat up 20% money from your salary and 80% will go for your other commitments. Your earning should be in the range ₹5 to ₹6 lakh. At 15% end, your pay scale should have to be around ₹8 lakh. It works smoothly if you have no other large EMIs.
In annual terms, your salary estimates roughly ₹85 lakh to ₹1.2 crore without tax cuts. The surcharge and the 30% slab take a big bite at this level. It updates with time, calculating your in-hand salary according to the latest slabs for your financial year.
The rule is “20/4/10” to buy any luxury German car on your salary. It means 20% down payment from your salary to a 4-year loan. The running cost of the car plus an EMI should take your 10% of the income. Spending more of your income will keep you awake all night because of a burden.
Your monthly salary should be around ₹12 lakh to pay ₹1.2 lakh to run a BMW on road. But most people don’t earn that much in a month in a job so it is too expensive to buy a new BMW at ₹55 lakh. People eyeing that car mostly have business running around in the side or supporting their own family business
A few situations change the math in your favour:
- A bigger down payment. Put 40% down (₹22 lakh) and the EMI on a ₹33 lakh loan drops to about ₹68,500. Add ₹25,000 in running costs and you need around ₹4.7 lakh a month in hand.
- A longer tenure. Stretching to seven years cuts the EMI but raises total interest sharply. Fine for cash flow, costly overall.
- Business or variable income. If your pay swings, plan around your worst quarter, not your best.
How the 2 Series Gran Coupe Stacks Up Against Rivals
If you’re buying a BMW in India at this price, the realistic cross-shopping list is short. Audi A4, the Mercedes-Benz A-Class Limousine and the Audi Q3 as the 2 Series Gran Coupe’s direct competitors.
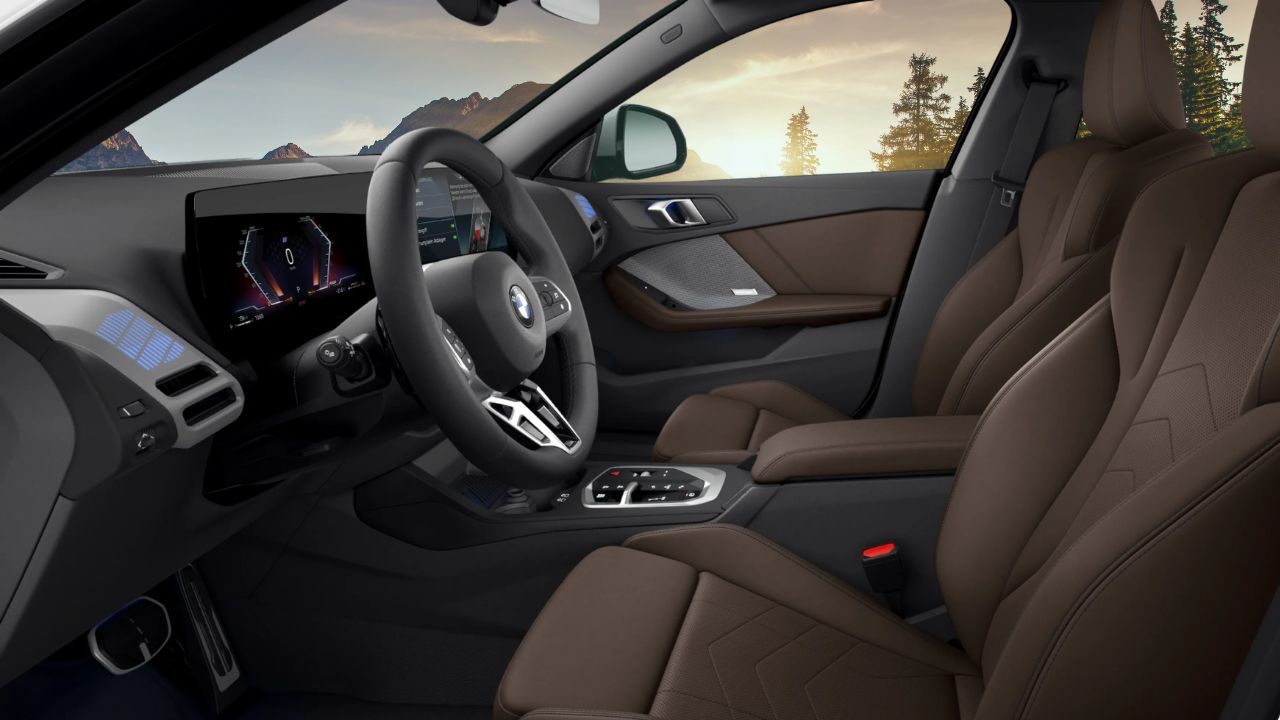
The BMW’s pitch is a driver-focused compact sedan with a coupe-like roofline, a curved display dashboard and a dual-clutch automatic. It’s the sportiest of the three on paper and the cheapest way into a BMW showroom.
| Variant | Engine | Power output | Torque | Transmission | Claimed mileage |
| BMW 218 M Sport | 1,499 cc, 3-cylinder BMW TwinPower Turbo petrol with 48V mild-hybrid system | 115 kW / 156 hp (154 bhp) | 230 Nm | 7-speed Steptronic DCT, front-wheel drive | 16.35 kmpl |
Both BMW 218 M Sport and BMW 218 M Sport Pro have the same specs but the 218 M Sport Pro is ₹3.10 lakh higher than the base model. BMW X1 petrol variant is ₹5.10 lakh higher and diesel variant is ₹7.10 lakh higher than the 218 M series in India. Price gets higher because luxury experiences are expensive with SUV body style, higher driving position, longer-wheelbase practicality.
The Mercedes A-Class Limousine is the closest rival for badge and price, and it tends to win on cabin tech and ride comfort but the car is discontinued in India. The Audi A4 is a size larger, which means more rear-seat space, but it usually costs more once you tick option boxes. Against the BMW X1’s ₹50.90–52.90 lakh range, the A4 Premium undercuts it by ₹4.02 lakh, but the A4 Technology costs ₹2.93 lakh more than the X1 petrol.
For a buyer deciding purely on affordability, the three cost within a few lakh of each other. Insurance and servicing are close too. The decision usually comes down to what you want from the car: the BMW for how it drives and the Audi for the space.
👉 5 Best Affordable SUVs Under 15 Lakhs In India
Buy a Used BMW at the Half Price
Depreciation is the hidden cost of a new luxury car, and it is brutal in the first three years. Estimates vary, but a drop of 35–45% in value across the first five years isn’t unusual for premium cars in India. Buying used lets someone else pay that bill.
A well-maintained 3-to-4-year-old BMW 3 Series or X1 typically lists between ₹25 lakh and ₹35 lakh. Run the same 20% down, 5-year, 9% loan on each end:
| Car price | Down payment | Loan | EMI | Running costs | Total monthly | Income needed (20% rule) |
| ₹25 lakh | ₹5 lakh | ₹20 lakh | ~₹41,500 | ₹15,000–20,000 | ~₹57,000–62,000 | ~₹2.9–3.1 lakh |
| ₹35 lakh | ₹7 lakh | ₹28 lakh | ~₹58,000 | ₹20,000 | ~₹78,000 | ~₹3.9 lakh |
So a post-tax income of roughly ₹3–3.9 lakh a month makes a used BMW comfortable, and the EMI is nearly half of what the new car demands. Buying a used BMW car can be risky if the warranty is ended, its repair cost will be too expensive. So check the certified paperwork of the car or choose a car which repair history and services records are available. Take an independent mechanic to inspect the car and keep extra budget for repairing in the first year.
Conclusion
If you want to afford a BMW in India with your salary then start with three questions. Do you have six months of expenses in an emergency fund, separate from the down payment? Is your income stable enough that a ₹1.2 lakh monthly commitment won’t keep you up at night? And have you finished the bigger goals, like a home, that a car loan would otherwise compete with?
If the answer to all three is yes and your take-home is near ₹6 lakh, the 2 Series Gran Coupe is a reasonable purchase. If your income is closer to ₹3–4 lakh, the used 3 Series or X1 gives you the badge without the strain. If you’re below that, the honest advice is to wait a year or two. A BMW will still be there, and so will the loan.
Before you walk into a showroom, take your city’s on-road quote, divide the loan by a bank’s EMI calculator, add ₹25,000 for running costs, and see whether that total sits under 20% of what lands in your account each month. If it does, go. If it doesn’t, you’ve just saved yourself a bad decision.
